On this page
Why this matters
Use this guide alongside our lookup and comparison tools to move from reading into action.
Introduction
SR-22 insurance is a specialized type of car insurance often required by drivers who have been deemed high-risk due to violations such as DUI, reckless driving, or driving without insurance. While SR-22 is not technically insurance itself, it is a certificate of financial responsibility that your insurance company files with your state to prove you meet minimum coverage requirements. Understanding the SR-22 insurance cost by state is crucial for drivers who need this coverage, as premiums can vary significantly depending on the region and individual risk factors.
What is SR-22 Insurance?
Before diving into costs, it’s important to understand what SR-22 insurance entails:
-
Certificate of Financial Responsibility: The SR-22 is a document, not an insurance policy. It demonstrates to the state that you carry the minimum liability coverage required by law.
-
High-Risk Drivers: Typically required for drivers with recent traffic violations, lapses in coverage, or serious accidents.
-
Duration: Most states require SR-22 insurance for 3 years, although the duration can vary depending on the offense and state regulations.
Because SR-22 insurance is tied to your driving record and state laws, costs are highly variable.
Factors Affecting SR-22 Insurance Cost
Several factors determine the cost of SR-22 insurance, including:
-
State Requirements
Insurance premiums vary because each state sets different minimum liability coverage and filing rules for SR-22. States like California and Florida may have higher rates due to higher average claim costs, whereas states like Texas or Arizona may be lower. -
Type of Violation
Costs increase if SR-22 is required due to a DUI or multiple traffic violations compared to a minor lapse in coverage. -
Driver Profile
Age, driving history, credit score, and prior insurance coverage all impact SR-22 insurance cost. Younger drivers or those with poor driving records typically pay more. -
Insurance Provider
Some companies specialize in high-risk coverage and offer more competitive SR-22 rates. Others may add hefty surcharges for filing the SR-22 certificate. -
Duration of Coverage
States often require SR-22 insurance for 3 years, but early cancellation or lapses can trigger additional fees or higher renewal rates.
Average SR-22 Insurance Cost by State
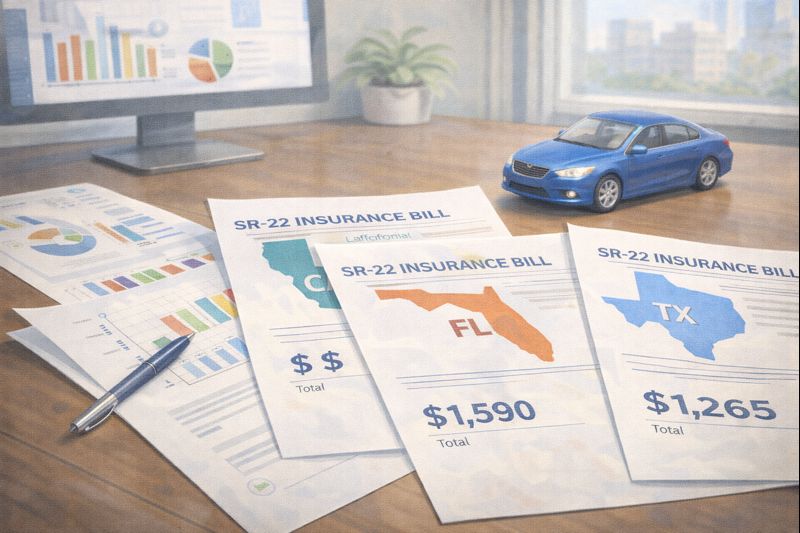
Here’s an overview of how SR-22 insurance costs can differ across the United States (approximate monthly premiums):
| State | Average SR-22 Monthly Premium | Notes |
|---|---|---|
| California | $150 – $250 | High traffic density increases premiums |
| Florida | $180 – $300 | Elevated DUI and accident rates |
| Texas | $100 – $200 | Moderate cost for high-risk drivers |
| New York | $160 – $280 | Strict liability coverage requirements |
| Arizona | $120 – $220 | Lower accident rates reduce cost |
| Illinois | $140 – $250 | High-risk driver surcharges common |
| Nevada | $130 – $240 | DUI-related filings higher |
| Pennsylvania | $120 – $210 | Competitive rates with online providers |
Tip: These rates are averages and can vary depending on your age, driving record, and insurer.
How to Reduce SR-22 Insurance Costs
Even if SR-22 insurance is mandatory, there are ways to keep costs manageable:
-
Shop Around
Compare quotes from multiple insurers. High-risk insurance specialists often provide better rates than mainstream providers. -
Maintain Continuous Coverage
Avoid lapses in coverage, as gaps can increase premiums and restart the filing process. -
Bundle Policies
Some insurers offer discounts if you bundle SR-22 coverage with home or renters insurance. -
Good Driver Programs
Completing defensive driving courses or state-approved safety programs may reduce SR-22 surcharges. -
Pay Annually
Paying your insurance annually rather than monthly can sometimes reduce administrative fees.
Common Misconceptions About SR-22 Insurance Costs
-
Myth 1: SR-22 insurance is extremely expensive for everyone
While it can be higher than standard insurance, rates vary widely by state and individual circumstances. -
Myth 2: SR-22 is a type of insurance
It is actually a filing certificate, not a standalone policy. Your insurance coverage (liability, collision, etc.) is what you pay for, and the SR-22 filing adds a small fee ($25–$50 typically). -
Myth 3: SR-22 is permanent
Most drivers only need SR-22 for 3 years, after which they can return to standard insurance.
Conclusion
Understanding the SR-22 insurance cost by state is essential for any high-risk driver navigating state requirements and insurance premiums. Costs vary depending on the state, type of violation, and driver profile, but careful planning, shopping around, and maintaining continuous coverage can help reduce expenses. By staying informed and compliant, drivers can fulfill SR-22 requirements and eventually return to standard insurance coverage without unnecessary financial burden.
Key Takeaways:
SR-22 is a certificate, not insurance, and demonstrates financial responsibility.
Costs vary by state and driver risk factors.
Maintaining continuous coverage and shopping for competitive quotes helps reduce premiums.
[fa_related_posts]
[fa_tools_cta]
Leave a Reply